You cannot buy property in Dubai with truly zero down payment. Even when a developer advertises "0% down", the 4% Dubai Land Department registration fee and administration charges are due when the sale is registered, unless the developer waives them, and banks will not lend the deposit. What you can find is a low entry: of the 150 Dubai off-plan projects on sale we track whose schedule lists the booking payment separately, seven ask 5% or less and 71 ask 10% or less. None asks for nothing. A low deposit spreads the payments; it does not reduce the price, and many low-deposit plans ask for a second instalment within weeks.
Key takeaways
- There is no true zero down payment in Dubai off-plan. The 4% Dubai Land Department fee and administration charges fall due when the sale is registered, unless the developer agrees to pay them.
- Of the 150 Dubai projects on sale we track whose schedule shows the booking payment as its own line, 70 ask 20% and 64 ask 10%. Seven ask 5% or less, the lowest being 2%. None asks for nothing (October 2026).
- "10% down" is the most common low entry. On an AED 800,000 home it is AED 80,000, plus AED 32,000 for the 4% fee and roughly AED 4,000 of charges: about AED 116,000 on day one.
- The lowest deposit is not always the lowest first year. A 5% booking with 15% due 30 days later and 1% a month after that needs about 35.5% of the price in year one.
- A DLD fee waiver is worth 4% of the price in cash. A 20% down payment with 1% a month and the fee waived needs about 32.5% of the price in year one on our worked example.
- Banks will not fund the down payment: the Central Bank requires it to come from your own resources, and off-plan loans are capped at 50% of value and usually drawn at handover.
- A low-deposit plan pushes the large payments to handover or after it. Check that you can fund the balance even if the bank lends less than you expect.
- If you stop paying, a developer may keep up to 25% or 40% of the price depending on how far the building is built, which can exceed everything a low-deposit buyer has paid.
01Can you buy property in Dubai with zero down payment?
Not with zero cash. "Zero down payment" in Dubai almost always describes something narrower than it sounds, and the difference matters when you plan your savings.
Three costs arrive whatever the advert says:
- The Dubai Land Department fee. Registering an off-plan sale carries a fee of 4% of the price. The department's initial sale registration service sets it out, together with a 90-day deadline from signing the contract.
- Administration and registration charges. The same service lists small fixed fees, and developers add their own administration fee, usually a few thousand dirhams.
- The first instalment. Even a plan marketed as "0% down" has a first payment somewhere. It may be small, it may be due a few weeks after booking, or it may be folded into the construction instalments.
What you can find is a low entry. Of the 150 Dubai off-plan projects on sale we track whose payment schedule lists the booking payment as its own line, seven ask 5% or less and 71 ask 10% or less. None asks for nothing at booking. The figures are from our own project data in October 2026.
This guide explains what the low-deposit offers really cost, how the common structures work, how much cash you need in the first year, how mortgages fit in and how to test whether a plan is affordable. It is general information, not personal financial advice; check your own position with a licensed adviser.
02What does "0% down" actually mean?
When you see "zero down payment", "0% down" or "no down payment" in an advert for Dubai property, it usually means one of three things.
| What the advert says | What it usually means | What you still pay at the start |
|---|---|---|
| "0% DLD" or "DLD fee waived" | The developer pays the 4% Dubai Land Department fee on your behalf | The booking deposit, often 10% to 20%, plus administration charges |
| "Pay just 2%" or "5% to book" | A small reservation amount, with the rest of the down payment due soon after | The deposit, the 4% fee and charges, then a larger instalment within weeks |
| "0% on booking" or "no down payment" | The first payment is part of the construction instalments rather than a separate booking line | The 4% fee and charges, plus the first construction instalment when it falls due |
The first type is the most valuable. A 4% fee on an AED 1,500,000 home is AED 60,000, and a developer who pays it saves you that amount in cash. In October 2026 Danube Properties was offering a 4% fee waiver across its projects when the buyer pays a 20% down payment, and Sobha Realty had waived the fee on individual units at Sobha One. Our offers page lists the current terms.
The second type is the most common source of confusion. A low booking amount reserves the unit, but the real down payment follows.
The third type is rare in the plans we track. A handful of developers publish a plan as a single "during construction" share that includes the booking payment. That is a presentation choice, not a free entry: the booking amount is still payable.
03Booking deposit, down payment and first instalment: three different things
Off-plan language in Dubai uses three terms loosely, and adverts often pick whichever sounds smallest.
- Booking deposit or reservation amount. The payment that takes the unit off the market. It can be as small as 2% of the price.
- Down payment. The full first share of the price the developer requires before the construction instalments begin. It is often 10% or 20%, and the booking deposit is part of it.
- First instalment. The first payment after the down payment, which on many low-deposit plans falls due 30 or 60 days after booking.
Sobha's offers show the difference clearly. Its September and October 2026 offers required "a 2% booking amount" to reserve a unit, while the payment plans themselves are 40/60 or 50/50, so most of the first 40% or 50% follows during construction. At The Willows at Sobha Sanctuary, the published plan is 2% on booking, 48% during construction and 50% on completion.
Coventry Residence in Dubai Industrial City takes a different route: 5% on booking, 15% thirty days later, then 1% a month for 24 months during construction, 20% on handover and 1% a month for 36 months after handover. The booking is small; the first month is not.
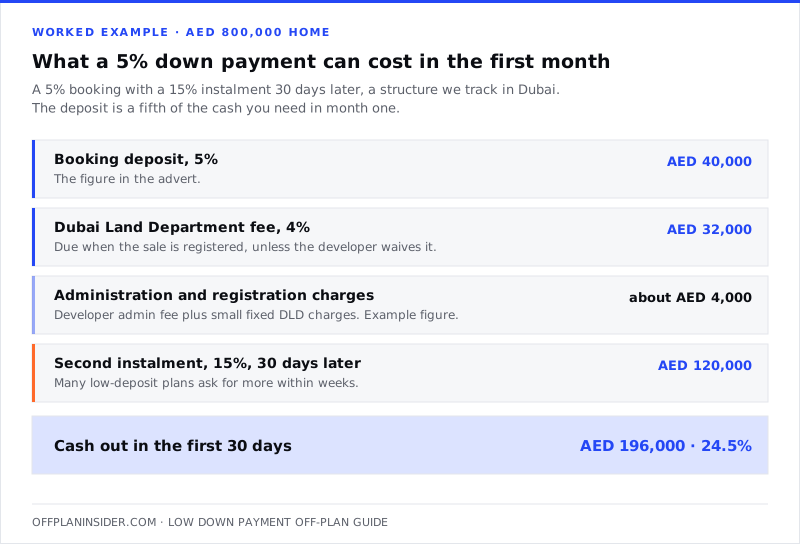
On an AED 800,000 home, that structure needs AED 40,000 at booking, AED 32,000 for the 4% fee, roughly AED 4,000 of charges and AED 120,000 a month later. That is AED 196,000, or 24.5% of the price, within 30 days. A plain 10% booking with nothing more for a year needs AED 116,000 in the same period.
04How low do off-plan down payments go in Dubai?
We track every Dubai off-plan project on OffPlan Insider against the developer's own payment plan. In October 2026, 182 of the Dubai projects on sale publish a schedule, and 150 of those show the booking payment as a separate line.
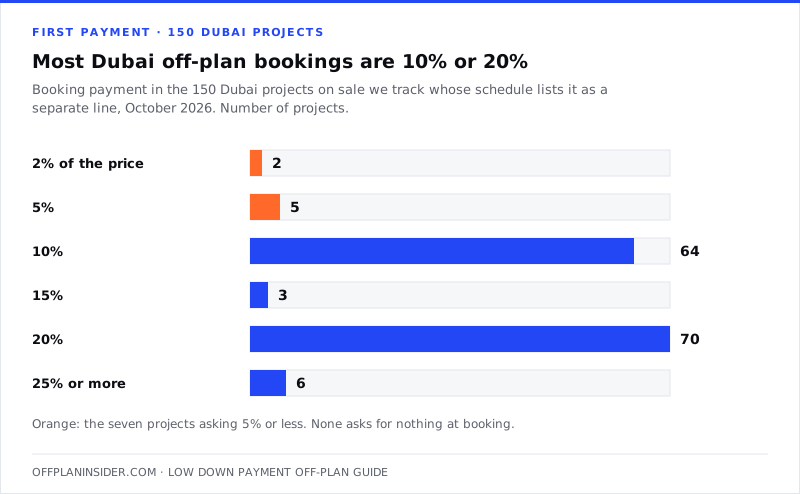
| Booking payment | Dubai projects | Share of the 150 |
|---|---|---|
| 2% | 2 | 1% |
| 5% | 5 | 3% |
| 10% | 64 | 43% |
| 15% | 3 | 2% |
| 20% | 70 | 47% |
| 25% or more | 6 | 4% |
Three points stand out.
- 10% and 20% are the market. Together they account for 134 of the 150 projects. If a plan is quoted without a booking figure, expect one of the two.
- Very low deposits are uncommon. Only seven Dubai projects ask 5% or less. Besides the two Sobha Sanctuary releases at 2% and Coventry Residence at 5%, they include Valencia at DAMAC Lagoons, Marea Residences on Dubai Islands, The Residences at The Dubai Beach EDITION and Rise by Athlon.
- Nobody asks for nothing. No Dubai project we track publishes a plan with nothing due at booking.
Outside Dubai, 5% bookings are more common in the projects we track. Across the UAE, 28 projects on sale ask 5% or less, 21 of them outside Dubai, mostly in Abu Dhabi and Sharjah. Registration rules and fees differ by emirate, so check them for the emirate you buy in.
Typical down payment by developer
Developers tend to use one booking figure across their projects. In the Dubai projects on sale we track, the patterns are clear.
| Developer | Dubai projects with a booking line | Booking payment in our data |
|---|---|---|
| Emaar | 22 | 10% on all 22 |
| Nshama | 8 | 10% on all 8 |
| Expo City Dubai | 7 | 10% on all 7 |
| Azizi | 9 | 10% on 8, 20% on 1 |
| Danube | 3 | 10% on all 3 |
| Binghatti | 16 | 20% on all 16 |
| Ellington | 7 | 20% on all 7 |
| Imtiaz | 8 | 20% on all 8 |
| Sobha | 4 | 2% on 2, 20% on 2 |
| DAMAC | 4 | 5% on 1, 10% on 1, 20% on 2 |
Offers move these figures. Through October 2026, Azizi ran a 10/90 plan on Azizi Riviera Phase 4 and two other projects, and Danube's October terms included a 30/70 plan starting with a 10% down payment. A temporary offer can make a 20% developer a 10% one for a few weeks, so check the offers page before you compare.
05Low deposit is not low price
A low deposit and a low price are different things, and adverts for "cheap" off-plan homes often blur them. The price decides what you owe in total; the plan decides when.
The lowest starting prices in our Dubai data, refreshed whenever we add or update a project:
- Lowest studio price we track: AED 474K at Nest Residence, International City.
- Lowest one-bedroom price we track: AED 621K at Nest Residence, International City.
- Lowest two-bedroom price we track: AED 909K at Nest Residence, International City.
- Projects with a home under AED 1 million: 71 in Dubai (November 2026).
If the total budget is the constraint, start with our cheapest off-plan apartments in Dubai and the homes under AED 1 million. If the cash available today is the constraint, the payment plan matters more than the price. Most buyers have both constraints, and the rest of this guide is about the second one.
06How 1%-a-month plans work
A 1%-a-month plan replaces a few large construction instalments with a monthly payment of 1% of the price. On an AED 800,000 home that is AED 8,000 a month; on AED 1,500,000 it is AED 15,000.
The structure usually has three parts: a down payment, the monthly instalments and a balance on handover. In October 2026, 14 of the Dubai projects on sale we track include a monthly instalment in their published plan. Our 1% monthly payment plan page lists them.
| Structure in our data | Example | How it runs |
|---|---|---|
| Monthly to handover | Celesto Tower | 20% on booking, 1% a month for 30 months, 50% on handover |
| Monthly before and after handover | Coventry Residence | 5% on booking, 15% after 30 days, 1% a month for 24 months, 20% on handover, 1% a month for 36 months |
| Monthly for most of the price | Peace Lagoons | 20% on booking, then 1% a month for 80 months |
| Developer-wide offer | Danube, October 2026 | 20% down, 1% a month during construction, 40% on handover, 4% fee waived with the down payment |
Monthly plans suit buyers with a steady income and modest savings. They are less forgiving than they look, for two reasons.
- They are calendar-linked. A monthly instalment falls due on a date, whether or not the building has progressed. The payment plans guide explains why that matters.
- They rarely start with a low deposit. Most of the monthly plans in our data begin with 20% down. The 1% a month is in addition to a conventional down payment, not instead of it.
07How post-handover plans work
A post-handover plan leaves part of the price to be paid after you receive the keys, usually in monthly or quarterly instalments over one to five years. It is developer credit, not a mortgage, and it runs alongside the service charge that starts at handover.
In October 2026, 20 of the Dubai projects on sale we track include a payment after handover. The share left until after handover runs from 25% to 50%. At Sky Residences in Expo City, for example, the plan is 10% on reservation, 35% during construction, 5% on completion and 50% in ten instalments of 5% every six months after handover. Our post-handover payment plans page lists the rest.
Post-handover plans lower the cash you need before completion. They do not lower the down payment much: most in our data still start at 10% or 20%. Some developers also charge more for the post-handover version of a plan. Danube's October 2026 terms, for instance, offered a post-handover option with a 5% premium on the price.
08How much cash do you need in year one?
The most useful number is not the deposit but the total you pay in the first 12 months, including fees. Here are four plans, each built from a structure in our project and offer data, on homes priced at AED 800,000 and AED 1,500,000.
Each example includes the 4% Dubai Land Department fee where it applies and roughly AED 4,000 of administration and registration charges. Monthly instalments are assumed to start in the first month after booking.
| Plan | Paid towards the price in year one | AED 800,000 home | AED 1,500,000 home |
|---|---|---|---|
| A. 10% booking, nothing else in year one (10/90-style) | 10% | AED 116,000 (14.5%) | AED 214,000 (14.3%) |
| B. 10% booking, 10% at two months, 5% at ten months (30/70-style) | 25% | AED 236,000 (29.5%) | AED 439,000 (29.3%) |
| C. 20% down, 1% a month, 4% fee waived | 32% | AED 260,000 (32.5%) | AED 484,000 (32.3%) |
| D. 5% booking, 15% at 30 days, then 1% a month | 31% | AED 284,000 (35.5%) | AED 529,000 (35.3%) |
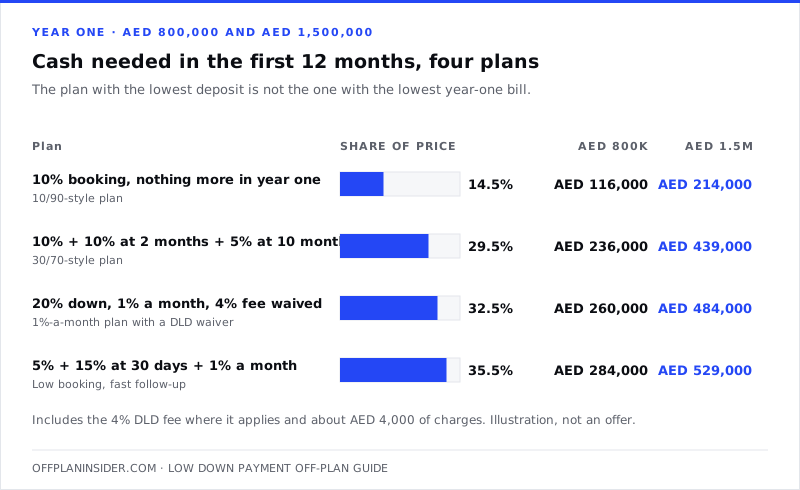
The arithmetic for the AED 800,000 home:
- Plan A: AED 80,000 deposit, AED 32,000 fee and AED 4,000 of charges, total AED 116,000.
- Plan B: AED 200,000 towards the price (25%), plus AED 32,000 and AED 4,000, total AED 236,000.
- Plan C: AED 256,000 towards the price (20% plus twelve payments of 1%), no fee and AED 4,000 of charges, total AED 260,000.
- Plan D: AED 248,000 towards the price (5% plus 15% plus eleven payments of 1%), plus AED 32,000 and AED 4,000, total AED 284,000.
And for the AED 1,500,000 home: Plan A is AED 150,000 plus AED 60,000 plus AED 4,000; Plan B is AED 375,000 plus AED 64,000; Plan C is AED 480,000 plus AED 4,000; Plan D is AED 465,000 plus AED 64,000.
Two lessons follow. The deposit alone tells you very little about affordability; the dated instalments in the first year tell you much more. And the 4% fee waiver in Plan C is worth AED 32,000 to AED 60,000 in cash, which is more than some of the deposit differences between plans.
You can run your own numbers with our payment plan calculator. For the full list of buying and holding costs, see the true cost of buying off-plan in Dubai.
09Where does the low deposit go? The handover balance
A low-deposit plan does not shrink the price; it moves it. The less you pay early, the more you owe at handover, and the handover payment is where low-deposit buyers most often struggle.
Take Plan A on the AED 800,000 home. If it is a 10/90 plan, with 10% paid at booking and the rest due on completion, AED 720,000 is due at handover. If you plan to borrow it, the mortgage rules decide whether you can.
| Plan shape | Due at handover on AED 800,000 | Due at handover on AED 1,500,000 |
|---|---|---|
| 10/90 | AED 720,000 | AED 1,350,000 |
| 20/80 | AED 640,000 | AED 1,200,000 |
| 30/70 | AED 560,000 | AED 1,050,000 |
| 40/60 | AED 480,000 | AED 900,000 |
| 60/40 | AED 320,000 | AED 600,000 |
On a 10/90 plan, the handover balance of AED 720,000 is 90% of the price. That is far above the 50% that banks may lend on property bought off-plan, and above the 80% cap on an expatriate's first completed home. A low-deposit buyer who expects to borrow the balance needs either savings for the gap, a post-handover plan, or a lender that treats the home as completed at the point of lending.
10Can a mortgage cover the down payment?
No. The Central Bank of the UAE's Regulations Regarding Mortgage Loans govern every home loan in the country, and they close off the idea of borrowing the deposit in three ways.
- The down payment must be your own money. Article 2 requires the down payment to come from the borrower's own resources, not from other borrowing such as a personal loan or credit card.
- Off-plan lending is capped at 50%. Article 3 sets a maximum loan-to-value of 50% for property bought off-plan, whatever the buyer's nationality, purpose or price.
- Your equity goes in first. Where a bank funds stage payments during construction, it must use the buyer's own share of the price before releasing loan money.
Since 1 February 2025, banks have also stopped financing the 4% registration fee and agency commission, as The National reported. Those costs are cash.
| Buyer and property | Maximum loan | Minimum own funds |
|---|---|---|
| Any buyer, property bought off-plan | 50% | 50% |
| Expatriate, first completed home, under AED 5M | 80% | 20% |
| Expatriate, first completed home, over AED 5M | 70% | 30% |
| Expatriate, second home or investment | 60% | 40% |
| UAE national, first completed home, AED 5M or less | 85% | 15% |
In practice, most mortgaged off-plan buyers pay the construction instalments themselves and borrow the handover balance, which the bank sizes against its own valuation and your income at that time. Our off-plan mortgage guide covers the rules, the debt-burden limit and the timing in detail.
The result for low-deposit buyers: the lower the deposit, the larger the handover balance, and the larger the share you may have to fund in cash if the bank's cap or valuation falls short.
11What the law protects, and what it leaves to you
A low deposit carries the same legal protection as a large one, as long as the project and the payment go through the proper channels.
| Covered by law | Not covered |
|---|---|
| Every payment goes into the project's escrow account under Law No. 8 of 2007, and the developer draws on it against certified progress | Whether you can afford the instalments that follow a low deposit |
| Your purchase is registered on the interim register, Oqood, under Law No. 13 of 2008 | Whether a bank will lend the handover balance, or how much |
| A developer must follow a set procedure, with a 30-day notice from the Dubai Land Department, before acting on a missed payment | The price at handover, which may be above or below what you agreed |
| The 4% registration fee is set by government; Executive Council Resolution No. 30 of 2013 sets the fee schedule | The developer's own administration fee, which is a matter of contract |
On the fee split: the department's service page divides the 4% equally, 2% from the buyer and 2% from the seller. The sale agreement can say otherwise, and on off-plan sales it usually places the whole 4% on the buyer. That is why a developer's "4% DLD waiver" is worth the full 4% to you. Check the clause in your contract.
12What happens if you cannot keep paying?
This is the risk low-deposit buyers underestimate most. Under Article 11 of Law No. 13 of 2008, as replaced by Law No. 19 of 2020, what a developer may keep after a default depends on how far the project is built, as a share of the price rather than of what you have paid.
- Under 60% built: the developer may terminate and keep up to 25% of the price.
- 60% to 80% built: it may terminate and keep up to 40%.
- Over 80% built: it may keep the contract and claim the balance, ask for an auction, or terminate and keep up to 40%.
Apply that to a low-deposit buyer. On an AED 800,000 home, 25% is AED 200,000. A buyer who has paid a 10% deposit, AED 80,000, has paid less than the limit, so a termination could leave nothing to refund. The 4% fee and administration charges are separate and are not part of the calculation.
The lower your payments so far, the more of them you could lose. Our guide to what happens if you can't pay off-plan instalments explains the procedure, the refund rules and the five ways out that cost less than a default.
13Stress-test a low-deposit plan before you book
Run these five questions before you pay a reservation amount. If any answer is no, the low deposit is moving risk to later, not removing it.
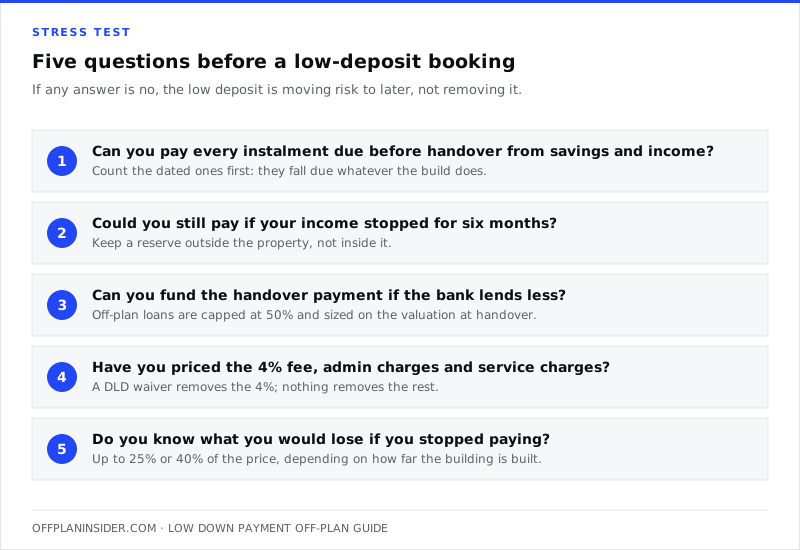
- Can you pay every instalment due before handover? List the dated instalments first. Calendar-linked payments fall due whatever the build does.
- Could you still pay if your income stopped for six months? Keep a reserve outside the property. A monthly plan on an AED 800,000 home is AED 8,000 a month, or AED 48,000 for six months.
- Can you fund the handover payment if the bank lends less? Work out the balance against a 50% loan, and again against a valuation 10% below your price.
- Have you priced every cost? The 4% fee, administration charges, and the service charge and other running costs that begin at handover. A waiver removes the 4%; nothing removes the rest.
- Do you know what you would lose if you stopped paying? Up to 25% of the price below 60% construction, and up to 40% from 60% upwards.
A worked stress test
Take Plan D on an AED 1,500,000 home: 5% on booking, 15% after 30 days, 1% a month for 24 months, 20% on handover and 1% a month for 36 months after handover.
- First month: AED 75,000 deposit, AED 60,000 fee, about AED 4,000 of charges and AED 225,000 at 30 days, total about AED 364,000.
- Each month for two years: AED 15,000.
- At handover: AED 300,000, plus the first service charge bill.
- After handover: AED 15,000 a month for three years, alongside the service charge.
- If your income stopped in year two: with 20% plus about a year of 1% instalments paid, roughly AED 480,000 towards the price, a termination under 60% construction lets the developer keep up to AED 375,000.
The plan is affordable for a buyer with about AED 364,000 available at the start and AED 15,000 a month of spare income for five years. It is not affordable for a buyer whose savings end at the 5% deposit.
14Who a low-deposit plan suits, and who it does not
| Suits | Does not suit |
|---|---|
| A buyer with steady income who can meet monthly or quarterly payments comfortably | A buyer whose savings stop at the deposit |
| A buyer who will pay the handover balance from savings or the sale of another asset | A buyer relying on a mortgage for more than half of the price at handover |
| An end user who will live in the home and can hold through a flat market | A buyer planning to resell before handover to fund the balance |
| A buyer comparing plans on the year-one total, not the deposit | A buyer choosing a project only because its deposit is the smallest |
Reselling before handover to escape the later instalments is possible, but it depends on the developer's resale rules, on how much you have paid and on the market at the time. Many developers require a set share of the price to be paid before they allow an assignment. Our guide to selling off-plan before handover covers the conditions.
15How to compare low down payment offers
When you have two or three options, put them side by side on the same terms.
| Question | Why it matters |
|---|---|
| What is due in the first 30, 90 and 365 days, in dirhams? | The deposit is often the smallest of the early payments |
| Is the 4% fee paid by me, shared, or waived? | A waiver is worth 4% of the price in cash |
| What is the administration fee? | It is set by the developer and varies |
| Are instalments linked to dates or to construction stages? | Dated instalments fall due even if the build slows |
| What is due at handover, and how will I pay it? | Off-plan mortgages are capped at 50% of value |
| Is the price the same on the low-deposit plan? | Some post-handover and deferred plans carry a premium |
| Is the offer time-limited? | Many offers run for days or weeks, and terms revert afterwards |
Our offers page lists current developer offers, including fee waivers, rebates and temporary plans, with the date we last checked each one. The payment plans hub groups projects by plan shape, from 30/70 to 60/40.
16Low down payment checklist
- Check the project on the Dubai Land Department's register and pay only into its escrow account. Our guide to checking an off-plan project and developer shows how.
- Get the full schedule in writing, with every instalment, its trigger and its date, before you pay a reservation amount.
- Add the fees: the 4% Dubai Land Department fee unless waived in writing, the administration fee and the small fixed registration charges.
- Total the first year, not just the deposit.
- Size the handover balance against a 50% loan and against a lower valuation.
- Keep a reserve of at least six months of instalments outside the property.
- Read the default clause and know what the developer may keep at each stage of construction.
- Compare offers on equal terms, including any price premium for a deferred or post-handover plan.
- Take advice. This guide is general information. A licensed adviser can check a plan against your income, savings and tax position.
17Key terms
- Booking deposit: the payment that reserves a unit, sometimes as small as 2% of the price.
- Down payment: the full first share of the price before construction instalments begin, usually 10% or 20%.
- DLD fee: the Dubai Land Department's 4% registration fee on a sale.
- DLD waiver: a developer offer to pay all or part of the 4% fee for you.
- Oqood: the department's interim register for off-plan sales, where the fee is paid.
- 1%-a-month plan: a plan with a monthly instalment of 1% of the price, usually after a 10% to 20% down payment.
- Post-handover plan: a plan with part of the price paid after you receive the keys.
- Loan-to-value (LTV): a mortgage as a share of the bank's valuation; capped at 50% for property bought off-plan.
- Escrow account: the project's regulated bank account, into which every off-plan payment must go.
18Where to go next
- Compare off-plan payment plans in the UAE, with the seven structures in use
- See every cost in the true cost of buying off-plan in Dubai
- Plan the handover balance with our off-plan mortgage guide
- Homes by budget: under AED 1 million and AED 1 to 2 million
- Projects with 1% monthly plans and post-handover plans
- Current developer offers, including DLD fee waivers
- Homes closer to completion, with less time paying instalments: projects near handover
- Get a free shortlist of projects that fit your budget and the cash you have today
ProjectsProjects mentioned in this guide.
FAQQuestions buyers ask.
Can I buy property in Dubai with zero down payment?
Not with zero cash. Even when a developer advertises 0% down, the 4% Dubai Land Department fee and administration charges are payable when the sale is registered, unless the developer waives them. Among the Dubai projects we track that show the booking payment separately, the lowest is 2% and the most common are 10% and 20%.
What is the minimum down payment for off-plan property in Dubai?
There is no legal minimum for a developer payment plan; the developer sets it. Across the 150 Dubai projects on sale we track with a separate booking line, the range runs from 2% to 60%. Seven ask 5% or less, 64 ask 10% and 70 ask 20% (October 2026). If you use a mortgage on a completed home, the Central Bank sets a minimum of 20% for an expatriate's first home under AED 5 million.
Are 0% down payment apartments in Dubai real?
The phrase usually describes one of three things: a developer paying the 4% Dubai Land Department fee for you, a booking deposit that is small but followed quickly by larger instalments, or a plan where the first instalment is folded into construction payments. None means you pay nothing. Ask for the full schedule, with dates, before you reserve.
How much cash do I need to buy a AED 800,000 off-plan apartment in Dubai?
On a 10% booking, about AED 116,000 on day one: AED 80,000 deposit, AED 32,000 for the 4% fee and roughly AED 4,000 of charges. Across the first year our four worked examples range from about AED 116,000 to AED 284,000, depending on how quickly the plan asks for its next instalments.
Which developers offer 10% down payment off-plan properties in Dubai?
Many. In the projects we track, a 10% booking is the standard at Emaar, Nshama and Expo City Dubai, and common at Azizi and Danube, among others. Offers change month to month: Azizi ran a 10/90 plan on three projects through October 2026. Our offers page lists the current terms.
What is a 1% monthly payment plan?
A plan where, after a down payment of typically 10% to 20%, you pay 1% of the price every month, often through construction and sometimes after handover. On an AED 800,000 home that is AED 8,000 a month. In October 2026, 14 of the Dubai projects on sale we track include a monthly instalment in their published plan.
Can I get a mortgage for the down payment on an off-plan property?
No. The Central Bank's mortgage regulations require the down payment to come from your own resources, not from other borrowing such as a personal loan. Off-plan mortgages are capped at 50% of value and in practice are usually drawn at or near handover, after you have paid the construction instalments yourself.
Is a low down payment off-plan property a good idea?
It depends on whether you can fund everything that follows. A low deposit makes it easier to start, but it moves the large payments to later, often to handover. Before booking, check the dated instalments, the handover balance against a 50% mortgage cap, and how much you would lose if you stopped paying. This is general information; check with a licensed adviser.
Sources & methodWhere these figures come from.
Sources
- Dubai Land Department: Request to register the initial sale
- Dubai Legislation Portal: ECR 30 of 2013
- Dubai Legislation Portal: Law No. (8) of 2007
- Dubai Legislation Portal: Law No. (13) of 2008
- Dubai Legislation Portal: Law No. (19) of 2020 Amending Law No. (13) of 2008 Regulating the Interim Real Property Register in the Emirate of Dubai
- Central Bank of the UAE Rulebook: Regulations regarding mortgage loans
- Central Bank of the UAE Rulebook: Article 2 risk management requirements
- Central Bank of the UAE Rulebook: Article 3 important ratios
- The National: UAE property mortgages fees
- gfsdevelopments.ae: Coventry residence
- sharafidevelopment.com: Marea
- sobharealty.com: The willows
- peacehomesdevelopment.com: Peace lagoons
- expocitydubai.com: Sky residences
What we could not verify
- The Dubai Land Department's service page splits the 4% fee equally between buyer and developer; that off-plan sale agreements usually put all 4% on the buyer comes from market practice and developer offer terms, and your contract decides.
- The roughly AED 4,000 of administration and registration charges in the worked examples is one developer's published admin fee used as an illustration; other developers charge different amounts.
- The four year-one plans are illustrations built from structures in our project and offer data; real contracts differ on when monthly instalments start and how dates move with the booking.
26 Oct 2026 · Reviewed by OffPlan Insider Research. First published 26 Oct 2026, updated 9 Nov 2026. Data as of 26 October 2026.