A DLD waiver in Dubai is a developer offer to pay the Dubai Land Department's 4% registration fee for you, or a stated part of it such as 2%. The government fee is not cancelled: the developer pays it to DLD when it registers your sale on Oqood. On an AED 1,000,000 home a full waiver saves AED 40,000 at booking. It does not cover the developer's administration charges, mortgage registration, service charges or anything after handover, and it often comes with a particular payment plan, so compare the whole offer, not the headline.
Key takeaways
- A DLD waiver means the developer pays the 4% Dubai Land Department fee, or the part it states, on your behalf. The fee schedule has no exemption; the law simply lets the parties agree who pays.
- A full 4% waiver saves AED 40,000 on an AED 1,000,000 home and AED 80,000 on AED 2,000,000. A 2% waiver saves half that.
- The saving arrives at booking, when the 4% would otherwise be paid. A rebate usually arrives at handover, and a discount lowers both the price and the 4% on it.
- Waivers are often tied to a payment plan, a booking window, a unit type or a down payment deadline. The plan that carries the waiver can ask for more of the price before handover.
- The waiver does not cover developer administration or Oqood charges, mortgage registration at 0.25% of the loan, trustee fees, title deed issuance at handover, service charges or agency commission.
- Get the waiver in the sale and purchase agreement, ask for the price with and without it, and keep your Oqood certificate as proof the sale and fee are registered.
- Current developer offers, including DLD waivers, change month to month and are listed on our offers page.
01What is a DLD fee waiver?
A DLD fee waiver is a developer offer to pay the Dubai Land Department's 4% registration fee for you, in full or in part. You may also see it advertised as "DLD paid", "0% DLD" or "registration fee waived".
The government fee itself is not cancelled. Executive Council Resolution No. 30 of 2013 charges 4% of the sale value to register a sale, and its schedule contains no exemption for promotions. What the resolution does allow is for the parties to agree who pays: Article 3 splits the fee equally between seller and buyer "unless agreed otherwise". A waiver is that agreement, with the developer paying instead of you.
This guide is about the offer, not the fee. How the 4% works, who pays it by default and when it is due are covered in our guide to the DLD fee in Dubai. Here we look at what a waiver saves, what it leaves out and how to compare it with other offers.
02How does a DLD waiver work on an off-plan purchase?
The developer registers your sale on Oqood and pays the 4% to DLD itself, instead of collecting it from you first. You receive the Oqood certificate as usual.
On any first off-plan sale, the developer registers the purchase through DLD's Oqood portal. DLD's initial sale registration page describes the process: the developer selects the unit, enters the details, attaches the documents, pays and submits, and the certificate is emailed to the purchaser. The page lists payment by Noqodi wallet or by deduction from the escrow account, and says the contract must be registered on the interim register within 90 days of signing.
Without a waiver, you pay the 4% to the developer, usually with or soon after the booking payment, and the developer passes it to DLD. With a waiver, that step disappears from your side. The registration and the certificate are the same either way.
Our guide to Oqood in Dubai explains what the certificate shows and how to check it in the Dubai REST app.
03What forms do DLD waiver offers take?
Most are one of a handful of shapes. The size of the waiver and the conditions attached to it vary more than the idea.
- A full 4% waiver. The developer pays the whole fee.
- A partial waiver, often 2%. The developer pays half the fee, and you pay the rest.
- A waiver tied to a payment plan. You choose between two plans, and only one carries the waiver. The waiver plan often asks for more of the price before handover.
- A waiver tied to the unit. The waiver applies to particular buildings, unit types, bedroom counts or units close to completion.
- A waiver with a deadline. It applies to bookings in a stated window, or only if you pay a set down payment, such as 20%, within a set number of days.
- A choice between a waiver and something else. For example a waiver on one plan, or a rebate or discount on another, but not both.
- A registration fee waiver in another emirate. Outside Dubai, the fee waived is that emirate's own registration fee, which is set locally and is not the DLD 4%.
Where to see what is on offer now. Offers change month to month, and some last a single day. Our offers page lists current developer offers, including DLD waivers, rebates, discounts and payment plan changes, with their dates and terms. New projects are on new launches.
04What does a DLD waiver cover, and what does it not?
It covers the DLD registration fee it names: 4%, or the part stated. Everything else in the purchase is still yours to pay unless the offer says otherwise in writing.
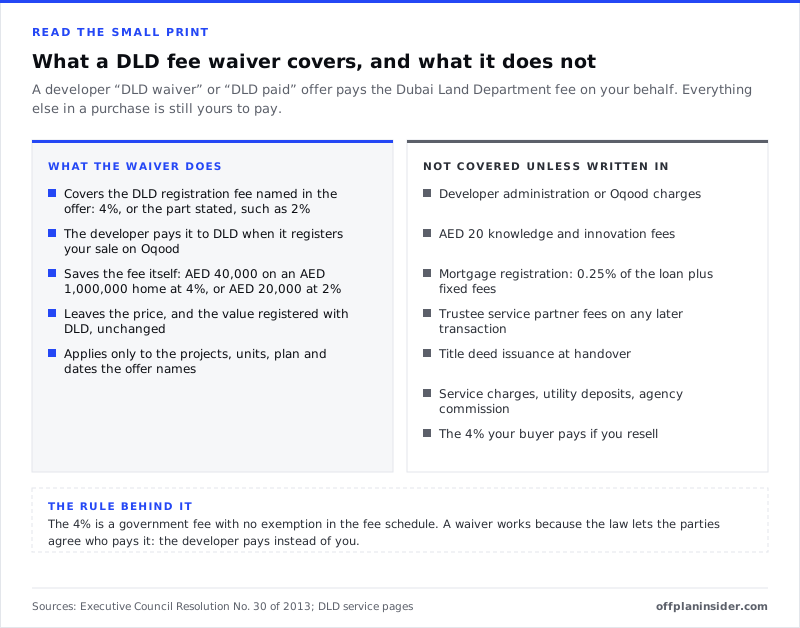
| Cost | Amount | Covered by a DLD waiver? |
|---|---|---|
| DLD registration fee | 4% of the sale value | Yes, in full or the part the offer states |
| Knowledge and innovation fees | AED 10 each | Ask; small, but not always included |
| Developer administration or Oqood charge | Set by each developer | Usually separate. Ask for the figure |
| Mortgage registration | 0.25% of the loan, plus fixed and service partner fees | No |
| Title deed issuance at handover | Small DLD issuance fees | No |
| Service charges and utility deposits | From handover | No |
| Agency commission | Where it applies | No |
| A buyer's 4% if you resell | 4% of their price | No; it is their fee |
The developer's own charges. Developers set an administration or Oqood processing charge for preparing and registering your contract. It is not a DLD fee, so a DLD waiver does not automatically include it. Ask for the figure in writing.
Mortgage costs. If you take a mortgage, usually at handover, DLD charges 0.25% of the loan plus fixed fees and a service partner fee. Our guide to the mortgage registration fee works through the amounts.
After handover. Service charges, district cooling and utility deposits begin when you take the keys. They are set out in our handover guide and our guide to service charges in Dubai.
05How much does a DLD waiver actually save?
Exactly the fee it covers. A full waiver saves 4% of the price; a 2% waiver saves 2%.
| Price | Full 4% waiver saves | 2% waiver saves |
|---|---|---|
| AED 750,000 | AED 30,000 | AED 15,000 |
| AED 1,000,000 | AED 40,000 | AED 20,000 |
| AED 1,500,000 | AED 60,000 | AED 30,000 |
| AED 2,000,000 | AED 80,000 | AED 40,000 |
| AED 3,000,000 | AED 120,000 | AED 60,000 |
| AED 5,000,000 | AED 200,000 | AED 100,000 |
The saving is real cash at the start. Without a waiver, the 4% is usually paid with or soon after the booking payment. On a 20% booking for an AED 1,000,000 home, that is AED 240,000 out of your account at once rather than AED 200,000. Since February 2025 banks have not financed the 4%, so the waiver lowers the cash you need to reserve.
It is a saving only against the same price. The waiver is worth its full amount if the unit costs the same with or without it. Ask the developer for the price of the same unit on the alternative plan or terms, and compare total cost, not just the fee line.
06Waiver, rebate, discount or a different plan: which saves more?
It depends on the size of each offer and when the money moves. A waiver saves the fee at booking; a rebate usually arrives at handover; a discount lowers the price and the 4% on it; a plan change moves when you pay.
The example below uses round numbers for one AED 1,000,000 home. It is an illustration, not any developer's offer. Every option starts with 20% at booking, and the 4% DLD fee is included where you pay it.
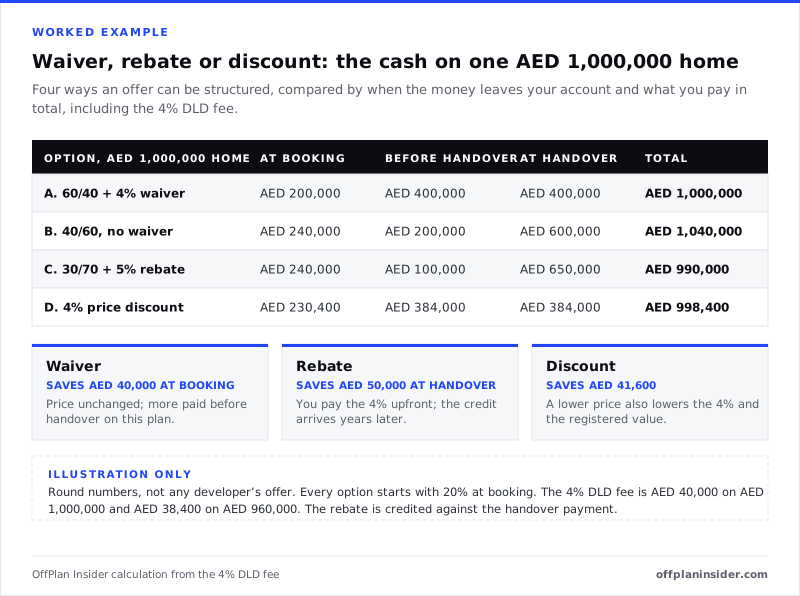
| Option | At booking | Before handover | At handover | Total paid |
|---|---|---|---|---|
| A. 60/40 plan with a 4% waiver | AED 200,000 | AED 400,000 | AED 400,000 | AED 1,000,000 |
| B. 40/60 plan, no waiver | AED 240,000 | AED 200,000 | AED 600,000 | AED 1,040,000 |
| C. 30/70 plan with a 5% rebate at handover | AED 240,000 | AED 100,000 | AED 650,000 | AED 990,000 |
| D. 4% price discount, 60/40 plan | AED 230,400 | AED 384,000 | AED 384,000 | AED 998,400 |
A against B: the waiver against a lighter plan
Both cost the same price, but A saves AED 40,000. In return, A asks for AED 400,000 before handover against AED 200,000 on B, so you pay AED 200,000 more during construction.
Whether that suits you depends on your cash. If you are paying construction instalments from savings, A is cheaper overall. If you need to keep cash in hand until handover, B may fit better despite costing more.
A against C: the waiver against a rebate
C costs AED 10,000 less in total, because a 5% rebate on AED 1,000,000 is AED 50,000, more than the AED 40,000 fee. But on C you pay the 4% yourself at booking and receive the rebate years later, credited against the handover payment.
Check three things about a rebate. When exactly is it credited, and is it cash or a reduction of the balance? Does it depend on paying every instalment on time? And what happens to it if you assign the contract before handover?
A against D: the waiver against a discount
A 4% discount saves a little more than a 4% waiver: AED 41,600 against AED 40,000. That is because the DLD fee is charged on the price, so a lower price also means a lower fee: 4% of AED 960,000 is AED 38,400.
A discount also lowers the value registered with DLD, while a waiver keeps it. That can matter to you later. If a Golden Visa is part of your plan, the AED 2,000,000 threshold is applied to DLD's valuation of the property; our Golden Visa guide explains the test.
What if you will use a mortgage at handover?
The handover payment matters as much as the total. The Central Bank caps lending on property bought off-plan at 50% of its value, and the bank lends against its own valuation.
On the numbers above, A leaves AED 400,000 to pay at handover, within a 50% loan of AED 500,000. C leaves AED 650,000, so even a full 50% loan leaves AED 150,000 to find in cash. Our guide to off-plan mortgages explains the cap, and the payment plan calculator shows the cash for any plan.
07When is a waiver worth less than it looks?
When something else in the offer moves. A waiver is a saving of 4% only if the price, the plan and your other costs stay the same.
- The price is different. If the same unit is listed at a different price on the waiver terms, compare totals.
- The plan is heavier. A plan that front-loads the price can cost you flexibility, as in option A above.
- The conditions are tight. A waiver that depends on paying 20% within a set number of days is lost if the payment is late.
- The extras are charged separately. The developer's administration charge, parking or other items are still payable.
- You plan to resell early. Your buyer pays their own 4%, so the waiver benefits only you, and some offers carry conditions on early assignment.
None of this makes a waiver a poor offer. On a unit you would buy anyway, at the same price, a full waiver is 4% you do not have to find. The point is to check what is being compared.
08What should I get in writing?
The waiver is a contract term, so what counts is what your signed documents say, not the brochure or the advert.
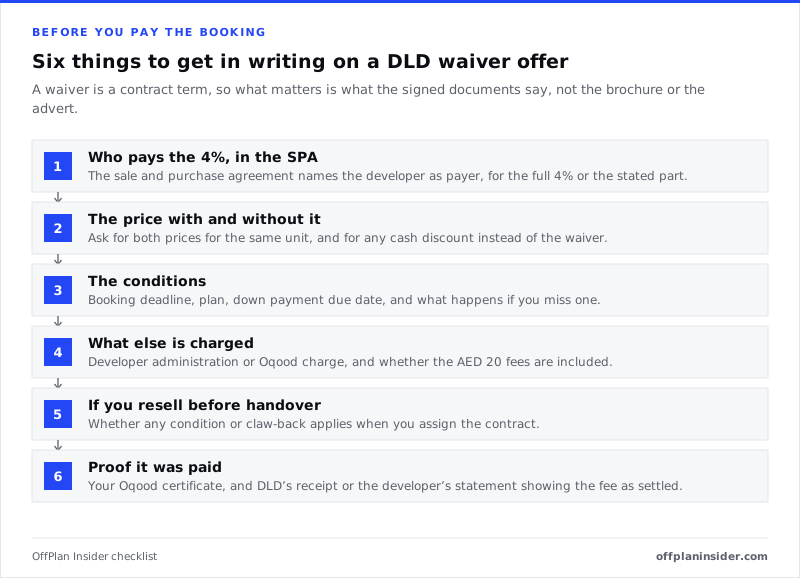
- Who pays the 4%. The reservation form and the sale and purchase agreement should say the developer pays the DLD registration fee, and how much of it.
- The price with and without it. Ask for both, for the same unit, and for any cash discount offered instead.
- The conditions. The booking window, the payment plan, the down payment and its deadline, and what happens if you miss one. Ask directly whether you would then owe the 4%.
- What else is charged. The developer's administration or Oqood charge, and whether the AED 20 knowledge and innovation fees are included.
- Resale and cancellation. What happens to the waiver, and to any rebate, if you assign the contract before handover or the contract is ended.
- Proof of registration. Your Oqood certificate, and a statement showing the DLD fee as settled. If the certificate has not arrived within a few weeks of booking, ask the developer for the registration status in writing.
Our guide to checking an off-plan project shows how to confirm the project and your registration in the Dubai REST app.
09Can I get a DLD waiver on a ready or resale home?
Not as a DLD exemption, but the same principle applies: you can agree who pays. On a resale the law's default is an equal split of the 4%, and most contracts put it all on the buyer.
A seller who wants a quicker sale may agree to pay their 2%, or more. On AED 2,000,000, the seller's half is worth AED 40,000 to you. Put the agreement in the memorandum of understanding; our guide to Form F shows where the clause goes.
A resale also carries a trustee fee and fixed DLD charges that an off-plan purchase does not. Our guide to registration trustee fees lists them.
10Is there another way to ease the 4%?
Yes, if you are a first-time buyer. DLD's First-Time Home Buyer Programme lets eligible buyers pay DLD registration fees in interest-free instalments through eligible credit cards.
It does not reduce the fee; it spreads it. It is open to UAE residents aged 18 or over who do not already own freehold residential property in Dubai, buying a home valued under AED 5 million, and its benefits can be used with one partner developer and one partner bank. The details are in our DLD fee guide. If a project has no waiver on offer, it can still lower the cash you need at booking.
11How do waivers work outside Dubai?
The idea is the same, but the fee is different. Each emirate's land department sets its own registration fee, so a "registration fee waiver" in Sharjah, Abu Dhabi or Umm Al Quwain covers that emirate's fee, not the DLD 4%.
Check the fee with the emirate's land department before you value the offer. Our guides to buying in Sharjah, buying in Abu Dhabi, Ajman and Ras Al Khaimah set out each emirate's fees and process.
12Common mistakes with DLD waiver offers
- Treating the waiver as a discount on everything. It covers one fee, not the developer's charges or later costs.
- Comparing headlines, not totals. Put each option's full cost and payment dates side by side.
- Missing the condition. A late down payment can lose the waiver.
- Relying on the advert. If the SPA does not say the developer pays, the default applies.
- Forgetting the handover payment. A plan that saves the fee but loads the handover can leave a gap a mortgage will not fill.
- Assuming the waiver passes to a buyer. A resale is a new sale with its own 4%.
13Key terms
- DLD fee. The Dubai Land Department's 4% fee for registering a property sale.
- DLD waiver. A developer offer to pay that fee, or part of it, for you.
- Rebate. A sum, usually a percentage of the price, credited to you later, often at handover.
- Discount. A lower price, which also lowers the 4% fee charged on it.
- Oqood. DLD's interim register for off-plan sales, where the developer registers your purchase.
- SPA. The sale and purchase agreement between you and the developer.
14Where to go next
Start with the live list of current offers on our offers page, then compare each one against the same unit without it. For the fee itself, read our DLD fee guide; for every other cost of buying, read the true cost of buying off-plan in Dubai. To see how a plan spreads the price, use the payment plan calculator or browse projects by plan, such as 60/40 or post-handover.
FAQQuestions buyers ask.
What does DLD waiver mean in Dubai?
It means a developer pays the Dubai Land Department's 4% registration fee for you, in full or in the part it states, as a sales offer. The fee is still paid to DLD; it is the payer that changes. Executive Council Resolution No. 30 of 2013 lets the parties agree who pays the fee, which is what makes the offer possible.
How much does a 4% DLD waiver save?
Exactly the fee it covers: 4% of the sale value. That is AED 40,000 on an AED 1,000,000 home, AED 60,000 on AED 1,500,000 and AED 80,000 on AED 2,000,000. A 2% waiver saves half those amounts. Other costs of the purchase are unchanged, so compare the offer with the price of the same unit without it.
Is a DLD waiver better than a discount?
It depends on the numbers. A 4% discount lowers the price, and because the 4% DLD fee is calculated on the price, it also lowers the fee: on AED 1,000,000 a 4% discount saves AED 41,600 against AED 40,000 for a 4% waiver. A discount also lowers the value registered with DLD. A waiver keeps the price the same.
Is a DLD waiver better than a rebate?
Compare the amount and the timing. A waiver saves the fee at booking. A rebate is usually a percentage of the price credited later, often against the handover payment, so it can be larger but arrives years after you have paid the 4% yourself. Check the conditions for receiving the rebate, and what happens to it if you resell before handover.
Does a DLD waiver include the Oqood fee?
Not necessarily. DLD's own registration charges on a first off-plan sale are the 4% fee and AED 20 in knowledge and innovation fees. Developers also charge their own administration or Oqood processing fee, which varies. Ask whether the waiver covers it, and get the answer in writing.
Do I have to pay the DLD fee at handover if it was waived?
No. The 4% belongs to the sale and is paid once, when the developer registers it on Oqood. At handover, when the Oqood converts to a title deed, only small issuance fees apply, whether or not the 4% was waived. If you take a mortgage, its registration fee of 0.25% of the loan is separate.
What happens to a DLD waiver if I resell before handover?
Your buyer is charged a new 4% on the price they pay; the waiver on your purchase does not pass to them. Some offers carry conditions that apply if you assign the contract early, so ask the developer before you book what happens to the waiver, and to any rebate, on resale.
Can I get a DLD fee waiver on a resale property?
Not from DLD, but you can negotiate who pays. On a resale the law splits the 4% equally between seller and buyer unless agreed otherwise, and most contracts put it all on the buyer. A seller can agree to pay part or all of it. Put the agreement in the memorandum of understanding.
Sources & methodWhere these figures come from.
Sources
- Dubai Legislation Portal: ECR 30 of 2013
- Dubai Land Department: Request to register the initial sale
- Dubai Land Department: A sale registration application associated with an initial mortgage
- Dubai Land Department: Property sale registration
- Dubai Land Department: Request for mortgage registration
- Dubai Land Department: First time home buyer overview
- Dubai Land Department: Frequently asked questions
- Central Bank of the UAE Rulebook: Regulations regarding mortgage loans
- The National: UAE property mortgages fees
What we could not verify
- Whether a rebate credited at handover changes the price registered with DLD, and therefore the 4% charged on it, could not be confirmed; the worked example assumes the 4% is charged on the full contract price and the rebate is credited against the handover payment.
- What happens to a waiver if the buyer misses a condition, cancels or assigns the contract before handover is set by each developer's terms and sale and purchase agreement, not by DLD; the text tells buyers to ask and get the answer in writing.
- Whether a waiver covers the AED 20 knowledge and innovation fees and the developer's own administration or Oqood charge varies by offer and is given as on request.
7 Nov 2026 · Reviewed by OffPlan Insider Research. First published 7 Nov 2026.